See whether Helium helps you make better-informed decisions. Try every Pro Trader feature for 30 days. No credit card required.
Try every Pro Trader feature for 30 days. No credit card required.
September 16, 2026 · 0 shares
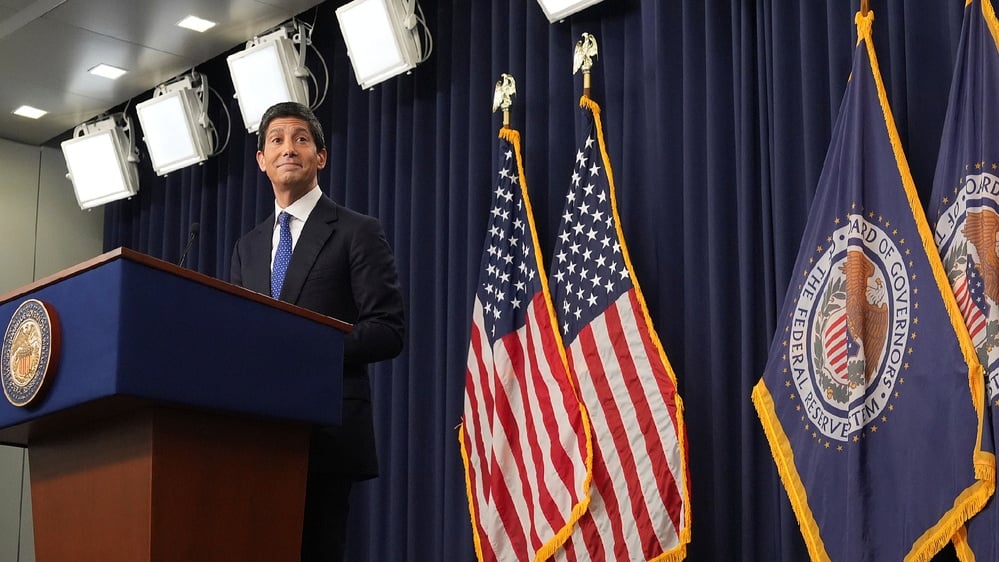
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed.
Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
·
6 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed.
Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
·
4 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed.
Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
·
6 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed.
Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
·
4 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 16, 2026 · 0 shares
The coverage frames the Fed's quarter-point hike as a politically charged but market-expected move, emphasizing White House pressure and central-bank independence.
Automated analysis; not human reviewed.
Limitations: The supplied text is a truncated, interleaved extraction with some incomplete paragraphs and apparent sidebar items; classification is based mainly on the clear economic and political reporting segments.
·
2 of 54 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 2 of 2 scored dimensions.
Claim: The publisher asserts without hedging that the rate hike will certainly make the president angry.
“The fresh hike will be sure to anger Mr Trump” · exact text match
Why: The phrase 'will be sure to' expresses certainty about a future emotional response, which the article does not and cannot establish.
Claim: The report attributes key policy and market statements to named institutions and officials.
“according to the central bank's Summary of Economic Projections” · exact text match
“JP Morgan's global head of economic research, Bruce Kasman, said market expectations surrounding interest rates had shifted across the developed world since the beginning of the year.” · exact text match
Why: Named attribution and direct quotation provide visible sourcing for most assertions.
The supplied text is a truncated, interleaved extraction with some incomplete paragraphs and apparent sidebar items; classification is based mainly on the clear economic and political reporting segments.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed.
Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
·
4 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 17, 2026 · 0 shares
Frames the Fed's rate hike as welcomed by stocks while casting Trump's opposition as an outlier, using emotional language to create a mildly sensational, market-positive narrative.
Automated analysis; not human reviewed.
Limitations: Analysis is based solely on a two-line headline; the publisher's full argument and supporting evidence were unavailable.
·
3 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 3 of 3 scored dimensions.
Claim: The headline presents an interpretive, emotionally colored characterization of market and presidential reactions rather than neutral factual reporting.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: The terms 'loving' and 'hates' express subjective emotional states attributed to the stock market and Trump.
Claim: The headline uses emotional and hyperbolic language to frame the Fed rate hike and reactions.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: 'Loving' and 'hates' are emotionally charged and colloquial, turning a market reaction into a dramatic contrast.
Claim: The headline conveys a positive market outlook by describing stocks as loving the rate hike.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: Characterizing stocks as 'loving' the hike frames the market reaction favorably, giving the headline a mildly bullish tone.
Analysis is based solely on a two-line headline; the publisher's full argument and supporting evidence were unavailable.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed.
Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
·
6 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed.
Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
·
4 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed.
Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
·
6 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 13, 2026 · 0 shares
Dovish framings are foregrounded, presenting the likely Fed hike as a Wall Street-driven "wall of mirrors" rather than an inflation response, while a competing forecast of further hikes is included.
Automated analysis; not human reviewed.
Limitations: The supplied text includes appended headline cards and disclosure boilerplate, so only the Fed-rate-hike item was treated as substantive article content; no external verification of the economic claims was possible.
·
6 of 54 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 6 of 6 scored dimensions.
Claim: The headline and lead framing assert a market-driven motive for the expected Fed hike while the article still includes attributed data.
“Fed rate hike is about Wall Street, not inflation, says economist.” · exact text match
“Fast-forward two years, and markets are assuming the Fed has no choice but to embark on a rate-hike cycle next week, even as the core CPI has fallen to a five-year low of 2.4%.” · exact text match
Why: The selection of the headline and the juxtaposition highlight an interpretive claim, but the body uses attributed quotes and includes a competing forecast.
Claim: The report relays forecasts and attributed opinions rather than issuing policy commands.
“A Federal Reserve rate hike next Wednesday — likely 25 basis points — is essentially universally expected at this point.” · exact text match
“We now expect three rate hikes by early 2027” · exact text match
Why: No publisher-authored 'should' or directive appears; evaluative lines are in quoted material.
Claim: The selected commentary stresses that rate hikes harm demand and are not an inflation cure, a dovish-leaning framing.
“No material change in inflation outlook, but a hike to calm Wall Street.” · exact text match
“They reduce demand, investment, employment, and household purchasing power.” · exact text match
Why: Thorne's critiques are given prominent placement and align with the headline; Swonk's forecast of more hikes appears later as a counterpoint.
Claim: Visible sourcing and specific statistics support the report's trustworthiness.
“Goldman Sachs late Friday became the last of the major banks to retract its forecast of no rate hike next week.” · exact text match
“Based on the CPI data, the PCE Index, which is the Fed’s preferred inflation gauge (not CPI), is likely to be higher by 0.4% in August, with core up 0.3%, she added.” · exact text match
Why: Named sources, direct quotes, and concrete figures provide internal credibility; no independent external verification is visible.
Claim: The article consistently attributes substantive claims to named institutions and economists and includes a competing view.
“said the bank.” · exact text match
“said Diane Swonk, chief economist at KPMG.” · exact text match
Why: Attribution is explicit for the Goldman forecast, Thorne's critique, and Swonk's projections, and the report does not present opinions as unqualified facts.
Claim: The article uses precise quantitative distinctions and technical context.
“That would put the annualized pace of core PCE at 3.4% — far further above the Fed’s 2% target than core CPI.” · exact text match
“Super core services, she said, were up a particularly hot 0.5% and up 3% year-over-year.” · exact text match
Why: The text explains why PCE differs from CPI and cites multiple inflation measures, showing analytical depth.
The supplied text includes appended headline cards and disclosure boilerplate, so only the Fed-rate-hike item was treated as substantive article content; no external verification of the economic claims was possible.
September 16, 2026 · 0 shares
A potential Fed rate hike is framed as a possible bullish catalyst, selecting analyst forecasts that predict a positive stock-market reaction while giving little weight to bearish scenarios.
Automated analysis; not human reviewed.
Limitations: The supplied text is a partial excerpt with duplicated boilerplate, no byline or dateline, and at least one truncated quotation, so the publisher's original framing context is incomplete.
·
10 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 5 of 10 scored dimensions.
Claim: The report is structured as a thesis-driven argument rather than a neutral presentation of facts.
“The case for a 'bullish shock' to stocks if the Fed hikes rates.” · exact text match
“there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The title explicitly makes a 'case,' and the content advances a contrarian interpretation using attributed analyst opinion.
Claim: The writing uses colorful and dramatic language to describe the possible market outcome.
“"Wednesday may be bullish no matter which door the FOMC walks through," Zeberg said.” · not found in supplied text
“"Falling yields and a falling dollar: the classic fuel of a bull market's final advance."” · not found in supplied text
Why: Phrases like 'bullish shock' and 'final advance' inject dramatic imagery into what is otherwise a routine market preview.
Claim: The report selects and emphasizes only bullish interpretations of a potential Fed rate hike.
“"Let's call it the bullish shock effect," he added of a potential surge in stocks on the Fed decision.” · not found in supplied text
“"Wednesday may be bullish no matter which door the FOMC walks through," Zeberg said.” · not found in supplied text
Counterevidence:
“"That's the opposite of what typically happens when the Fed hikes.
Higher rates tighten financial conditions and make the macro climate less favorable to risk assets."”
· not found in supplied text
Why: The lede suggests a hike 'could actually spark a renewed rally,' and every quoted forecaster predicts a positive market reaction; no bearish forecaster is included.
Claim: The forward-looking market outlook presented is uniformly positive.
“"Thus, we are expecting a positive reaction either way," Lee said.” · not found in supplied text
Why: The article's case is built around the possibility of a rally and a 'positive reaction either way,' with no pessimistic forecast featured.
Claim: The report describes possible market behavior and analyst views without telling investors what to do.
“Investors aren't clamoring for a Fed rate hike, but there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The wording is descriptive and conditional ('there's a chance,' 'if'), with no direct recommendation or imperative.
Claim: The article is a commentary-style case built on analyst opinions and forecasts.
“The case for a 'bullish shock' to stocks if the Fed hikes rates.” · exact text match
“"If the Fed hikes, this is priced in. If the Fed is on hold, it is a surprise dovish move.
Thus, we are expecting a positive reaction either way," Lee said.”
· not found in supplied text
Why: It argues for a specific market outlook using attributed opinions, rather than reporting a settled event.
Claim: The market reaction is reduced to a binary hike-or-hold scenario, both of which are assumed positive.
“"If the Fed hikes, this is priced in. If the Fed is on hold, it is a surprise dovish move.
Thus, we are expecting a positive reaction either way," Lee said.”
· not found in supplied text
Why: The quoted thesis treats only two possible Fed outcomes and ignores other variables such as forward guidance, projections, or a hawkish hold.
Claim: The report supports its thesis with named sources, direct quotes, and specific market data.
“Scott Chronert, the head of US equity strategy at Citi Research, said this week.” · exact text match
“Thomas Lee, a market permabull and the head of research at Fundstrat, said he believes markets are primed for a positive reaction no matter what the Fed does at the end of its meeting.” · exact text match
Why: Attribution is specific and quotes are direct, and the piece includes concrete probabilities and index/yield figures; credibility is limited by the one-sided selection of bullish forecasts.
Claim: The article centers on hypothetical future market reactions rather than realized outcomes.
“there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The entire piece is a pre-FOMC forecast about what could happen if the Fed hikes, holds, or signals resolve.
Claim: The article presents a structured contrarian argument with stated reasoning and supporting data.
“But there are two main reasons a hike could actually be bullish this time around, analysts say:” · exact text match
Why: It acknowledges the conventional negative view and then lays out a two-part rationale with attributed forecasts and market figures, though it does not critically test that rationale.
The supplied text is a partial excerpt with duplicated boilerplate, no byline or dateline, and at least one truncated quotation, so the publisher's original framing context is incomplete.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed. Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone. · 6 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed. Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence. · 4 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed. Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone. · 6 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 17, 2026 · 0 shares
Frames the Fed's rate hike as welcomed by stocks while casting Trump's opposition as an outlier, using emotional language to create a mildly sensational, market-positive narrative.
Automated analysis; not human reviewed. Limitations: Analysis is based solely on a two-line headline; the publisher's full argument and supporting evidence were unavailable. · 3 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 3 of 3 scored dimensions.
Claim: The headline presents an interpretive, emotionally colored characterization of market and presidential reactions rather than neutral factual reporting.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: The terms 'loving' and 'hates' express subjective emotional states attributed to the stock market and Trump.
Claim: The headline uses emotional and hyperbolic language to frame the Fed rate hike and reactions.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: 'Loving' and 'hates' are emotionally charged and colloquial, turning a market reaction into a dramatic contrast.
Claim: The headline conveys a positive market outlook by describing stocks as loving the rate hike.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: Characterizing stocks as 'loving' the hike frames the market reaction favorably, giving the headline a mildly bullish tone.
Analysis is based solely on a two-line headline; the publisher's full argument and supporting evidence were unavailable.
September 16, 2026 · 0 shares
A potential Fed rate hike is framed as a possible bullish catalyst, selecting analyst forecasts that predict a positive stock-market reaction while giving little weight to bearish scenarios.
Automated analysis; not human reviewed. Limitations: The supplied text is a partial excerpt with duplicated boilerplate, no byline or dateline, and at least one truncated quotation, so the publisher's original framing context is incomplete. · 10 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 10 scored dimensions.
Claim: The report is structured as a thesis-driven argument rather than a neutral presentation of facts.
“The case for a 'bullish shock' to stocks if the Fed hikes rates.” · exact text match
“there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The title explicitly makes a 'case,' and the content advances a contrarian interpretation using attributed analyst opinion.
Claim: The writing uses colorful and dramatic language to describe the possible market outcome.
“"Wednesday may be bullish no matter which door the FOMC walks through," Zeberg said.” · not found in supplied text
“"Falling yields and a falling dollar: the classic fuel of a bull market's final advance."” · not found in supplied text
Why: Phrases like 'bullish shock' and 'final advance' inject dramatic imagery into what is otherwise a routine market preview.
Claim: The report selects and emphasizes only bullish interpretations of a potential Fed rate hike.
“"Let's call it the bullish shock effect," he added of a potential surge in stocks on the Fed decision.” · not found in supplied text
“"Wednesday may be bullish no matter which door the FOMC walks through," Zeberg said.” · not found in supplied text
Counterevidence:
“"That's the opposite of what typically happens when the Fed hikes. Higher rates tighten financial conditions and make the macro climate less favorable to risk assets."” · not found in supplied text
Why: The lede suggests a hike 'could actually spark a renewed rally,' and every quoted forecaster predicts a positive market reaction; no bearish forecaster is included.
Claim: The forward-looking market outlook presented is uniformly positive.
“"Thus, we are expecting a positive reaction either way," Lee said.” · not found in supplied text
Why: The article's case is built around the possibility of a rally and a 'positive reaction either way,' with no pessimistic forecast featured.
Claim: The report describes possible market behavior and analyst views without telling investors what to do.
“Investors aren't clamoring for a Fed rate hike, but there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The wording is descriptive and conditional ('there's a chance,' 'if'), with no direct recommendation or imperative.
Claim: The article is a commentary-style case built on analyst opinions and forecasts.
“The case for a 'bullish shock' to stocks if the Fed hikes rates.” · exact text match
“"If the Fed hikes, this is priced in. If the Fed is on hold, it is a surprise dovish move. Thus, we are expecting a positive reaction either way," Lee said.” · not found in supplied text
Why: It argues for a specific market outlook using attributed opinions, rather than reporting a settled event.
Claim: The market reaction is reduced to a binary hike-or-hold scenario, both of which are assumed positive.
“"If the Fed hikes, this is priced in. If the Fed is on hold, it is a surprise dovish move. Thus, we are expecting a positive reaction either way," Lee said.” · not found in supplied text
Why: The quoted thesis treats only two possible Fed outcomes and ignores other variables such as forward guidance, projections, or a hawkish hold.
Claim: The report supports its thesis with named sources, direct quotes, and specific market data.
“Scott Chronert, the head of US equity strategy at Citi Research, said this week.” · exact text match
“Thomas Lee, a market permabull and the head of research at Fundstrat, said he believes markets are primed for a positive reaction no matter what the Fed does at the end of its meeting.” · exact text match
Why: Attribution is specific and quotes are direct, and the piece includes concrete probabilities and index/yield figures; credibility is limited by the one-sided selection of bullish forecasts.
Claim: The article centers on hypothetical future market reactions rather than realized outcomes.
“there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The entire piece is a pre-FOMC forecast about what could happen if the Fed hikes, holds, or signals resolve.
Claim: The article presents a structured contrarian argument with stated reasoning and supporting data.
“But there are two main reasons a hike could actually be bullish this time around, analysts say:” · exact text match
Why: It acknowledges the conventional negative view and then lays out a two-part rationale with attributed forecasts and market figures, though it does not critically test that rationale.
The supplied text is a partial excerpt with duplicated boilerplate, no byline or dateline, and at least one truncated quotation, so the publisher's original framing context is incomplete.
September 13, 2026 · 0 shares
Dovish framings are foregrounded, presenting the likely Fed hike as a Wall Street-driven "wall of mirrors" rather than an inflation response, while a competing forecast of further hikes is included.
Automated analysis; not human reviewed. Limitations: The supplied text includes appended headline cards and disclosure boilerplate, so only the Fed-rate-hike item was treated as substantive article content; no external verification of the economic claims was possible. · 6 of 54 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 6 of 6 scored dimensions.
Claim: The headline and lead framing assert a market-driven motive for the expected Fed hike while the article still includes attributed data.
“Fed rate hike is about Wall Street, not inflation, says economist.” · exact text match
“Fast-forward two years, and markets are assuming the Fed has no choice but to embark on a rate-hike cycle next week, even as the core CPI has fallen to a five-year low of 2.4%.” · exact text match
Why: The selection of the headline and the juxtaposition highlight an interpretive claim, but the body uses attributed quotes and includes a competing forecast.
Claim: The report relays forecasts and attributed opinions rather than issuing policy commands.
“A Federal Reserve rate hike next Wednesday — likely 25 basis points — is essentially universally expected at this point.” · exact text match
“We now expect three rate hikes by early 2027” · exact text match
Why: No publisher-authored 'should' or directive appears; evaluative lines are in quoted material.
Claim: The selected commentary stresses that rate hikes harm demand and are not an inflation cure, a dovish-leaning framing.
“No material change in inflation outlook, but a hike to calm Wall Street.” · exact text match
“They reduce demand, investment, employment, and household purchasing power.” · exact text match
Why: Thorne's critiques are given prominent placement and align with the headline; Swonk's forecast of more hikes appears later as a counterpoint.
Claim: Visible sourcing and specific statistics support the report's trustworthiness.
“Goldman Sachs late Friday became the last of the major banks to retract its forecast of no rate hike next week.” · exact text match
“Based on the CPI data, the PCE Index, which is the Fed’s preferred inflation gauge (not CPI), is likely to be higher by 0.4% in August, with core up 0.3%, she added.” · exact text match
Why: Named sources, direct quotes, and concrete figures provide internal credibility; no independent external verification is visible.
Claim: The article consistently attributes substantive claims to named institutions and economists and includes a competing view.
“said the bank.” · exact text match
“said Diane Swonk, chief economist at KPMG.” · exact text match
Why: Attribution is explicit for the Goldman forecast, Thorne's critique, and Swonk's projections, and the report does not present opinions as unqualified facts.
Claim: The article uses precise quantitative distinctions and technical context.
“That would put the annualized pace of core PCE at 3.4% — far further above the Fed’s 2% target than core CPI.” · exact text match
“Super core services, she said, were up a particularly hot 0.5% and up 3% year-over-year.” · exact text match
Why: The text explains why PCE differs from CPI and cites multiple inflation measures, showing analytical depth.
The supplied text includes appended headline cards and disclosure boilerplate, so only the Fed-rate-hike item was treated as substantive article content; no external verification of the economic claims was possible.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed. Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone. · 6 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed. Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence. · 4 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 16, 2026 · 0 shares
The coverage frames the Fed's quarter-point hike as a politically charged but market-expected move, emphasizing White House pressure and central-bank independence.
Automated analysis; not human reviewed. Limitations: The supplied text is a truncated, interleaved extraction with some incomplete paragraphs and apparent sidebar items; classification is based mainly on the clear economic and political reporting segments. · 2 of 54 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 2 scored dimensions.
Claim: The publisher asserts without hedging that the rate hike will certainly make the president angry.
“The fresh hike will be sure to anger Mr Trump” · exact text match
Why: The phrase 'will be sure to' expresses certainty about a future emotional response, which the article does not and cannot establish.
Claim: The report attributes key policy and market statements to named institutions and officials.
“according to the central bank's Summary of Economic Projections” · exact text match
“JP Morgan's global head of economic research, Bruce Kasman, said market expectations surrounding interest rates had shifted across the developed world since the beginning of the year.” · exact text match
Why: Named attribution and direct quotation provide visible sourcing for most assertions.
The supplied text is a truncated, interleaved extraction with some incomplete paragraphs and apparent sidebar items; classification is based mainly on the clear economic and political reporting segments.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed. Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence. · 4 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 13, 2026 · 0 shares
Dovish framings are foregrounded, presenting the likely Fed hike as a Wall Street-driven "wall of mirrors" rather than an inflation response, while a competing forecast of further hikes is included.
Automated analysis; not human reviewed. Limitations: The supplied text includes appended headline cards and disclosure boilerplate, so only the Fed-rate-hike item was treated as substantive article content; no external verification of the economic claims was possible. · 6 of 54 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 6 of 6 scored dimensions.
Claim: The headline and lead framing assert a market-driven motive for the expected Fed hike while the article still includes attributed data.
“Fed rate hike is about Wall Street, not inflation, says economist.” · exact text match
“Fast-forward two years, and markets are assuming the Fed has no choice but to embark on a rate-hike cycle next week, even as the core CPI has fallen to a five-year low of 2.4%.” · exact text match
Why: The selection of the headline and the juxtaposition highlight an interpretive claim, but the body uses attributed quotes and includes a competing forecast.
Claim: The report relays forecasts and attributed opinions rather than issuing policy commands.
“A Federal Reserve rate hike next Wednesday — likely 25 basis points — is essentially universally expected at this point.” · exact text match
“We now expect three rate hikes by early 2027” · exact text match
Why: No publisher-authored 'should' or directive appears; evaluative lines are in quoted material.
Claim: The selected commentary stresses that rate hikes harm demand and are not an inflation cure, a dovish-leaning framing.
“No material change in inflation outlook, but a hike to calm Wall Street.” · exact text match
“They reduce demand, investment, employment, and household purchasing power.” · exact text match
Why: Thorne's critiques are given prominent placement and align with the headline; Swonk's forecast of more hikes appears later as a counterpoint.
Claim: Visible sourcing and specific statistics support the report's trustworthiness.
“Goldman Sachs late Friday became the last of the major banks to retract its forecast of no rate hike next week.” · exact text match
“Based on the CPI data, the PCE Index, which is the Fed’s preferred inflation gauge (not CPI), is likely to be higher by 0.4% in August, with core up 0.3%, she added.” · exact text match
Why: Named sources, direct quotes, and concrete figures provide internal credibility; no independent external verification is visible.
Claim: The article consistently attributes substantive claims to named institutions and economists and includes a competing view.
“said the bank.” · exact text match
“said Diane Swonk, chief economist at KPMG.” · exact text match
Why: Attribution is explicit for the Goldman forecast, Thorne's critique, and Swonk's projections, and the report does not present opinions as unqualified facts.
Claim: The article uses precise quantitative distinctions and technical context.
“That would put the annualized pace of core PCE at 3.4% — far further above the Fed’s 2% target than core CPI.” · exact text match
“Super core services, she said, were up a particularly hot 0.5% and up 3% year-over-year.” · exact text match
Why: The text explains why PCE differs from CPI and cites multiple inflation measures, showing analytical depth.
The supplied text includes appended headline cards and disclosure boilerplate, so only the Fed-rate-hike item was treated as substantive article content; no external verification of the economic claims was possible.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed. Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone. · 6 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
Hawkish Fed/Credibility View
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed. Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone. · 6 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed. Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence. · 4 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed. Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone. · 6 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
Trump/White House Populist View
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed. Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone. · 6 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed. Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence. · 4 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 16, 2026 · 0 shares
The coverage frames the Fed's quarter-point hike as a politically charged but market-expected move, emphasizing White House pressure and central-bank independence.
Automated analysis; not human reviewed. Limitations: The supplied text is a truncated, interleaved extraction with some incomplete paragraphs and apparent sidebar items; classification is based mainly on the clear economic and political reporting segments. · 2 of 54 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 2 scored dimensions.
Claim: The publisher asserts without hedging that the rate hike will certainly make the president angry.
“The fresh hike will be sure to anger Mr Trump” · exact text match
Why: The phrase 'will be sure to' expresses certainty about a future emotional response, which the article does not and cannot establish.
Claim: The report attributes key policy and market statements to named institutions and officials.
“according to the central bank's Summary of Economic Projections” · exact text match
“JP Morgan's global head of economic research, Bruce Kasman, said market expectations surrounding interest rates had shifted across the developed world since the beginning of the year.” · exact text match
Why: Named attribution and direct quotation provide visible sourcing for most assertions.
The supplied text is a truncated, interleaved extraction with some incomplete paragraphs and apparent sidebar items; classification is based mainly on the clear economic and political reporting segments.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed. Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence. · 4 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 16, 2026 · 0 shares
The coverage frames the Fed's quarter-point hike as a politically charged but market-expected move, emphasizing White House pressure and central-bank independence.
Automated analysis; not human reviewed. Limitations: The supplied text is a truncated, interleaved extraction with some incomplete paragraphs and apparent sidebar items; classification is based mainly on the clear economic and political reporting segments. · 2 of 54 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 2 scored dimensions.
Claim: The publisher asserts without hedging that the rate hike will certainly make the president angry.
“The fresh hike will be sure to anger Mr Trump” · exact text match
Why: The phrase 'will be sure to' expresses certainty about a future emotional response, which the article does not and cannot establish.
Claim: The report attributes key policy and market statements to named institutions and officials.
“according to the central bank's Summary of Economic Projections” · exact text match
“JP Morgan's global head of economic research, Bruce Kasman, said market expectations surrounding interest rates had shifted across the developed world since the beginning of the year.” · exact text match
Why: Named attribution and direct quotation provide visible sourcing for most assertions.
The supplied text is a truncated, interleaved extraction with some incomplete paragraphs and apparent sidebar items; classification is based mainly on the clear economic and political reporting segments.
Dovish/Supply-Side Skeptic View
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed. Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone. · 6 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 13, 2026 · 0 shares
Dovish framings are foregrounded, presenting the likely Fed hike as a Wall Street-driven "wall of mirrors" rather than an inflation response, while a competing forecast of further hikes is included.
Automated analysis; not human reviewed. Limitations: The supplied text includes appended headline cards and disclosure boilerplate, so only the Fed-rate-hike item was treated as substantive article content; no external verification of the economic claims was possible. · 6 of 54 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 6 of 6 scored dimensions.
Claim: The headline and lead framing assert a market-driven motive for the expected Fed hike while the article still includes attributed data.
“Fed rate hike is about Wall Street, not inflation, says economist.” · exact text match
“Fast-forward two years, and markets are assuming the Fed has no choice but to embark on a rate-hike cycle next week, even as the core CPI has fallen to a five-year low of 2.4%.” · exact text match
Why: The selection of the headline and the juxtaposition highlight an interpretive claim, but the body uses attributed quotes and includes a competing forecast.
Claim: The report relays forecasts and attributed opinions rather than issuing policy commands.
“A Federal Reserve rate hike next Wednesday — likely 25 basis points — is essentially universally expected at this point.” · exact text match
“We now expect three rate hikes by early 2027” · exact text match
Why: No publisher-authored 'should' or directive appears; evaluative lines are in quoted material.
Claim: The selected commentary stresses that rate hikes harm demand and are not an inflation cure, a dovish-leaning framing.
“No material change in inflation outlook, but a hike to calm Wall Street.” · exact text match
“They reduce demand, investment, employment, and household purchasing power.” · exact text match
Why: Thorne's critiques are given prominent placement and align with the headline; Swonk's forecast of more hikes appears later as a counterpoint.
Claim: Visible sourcing and specific statistics support the report's trustworthiness.
“Goldman Sachs late Friday became the last of the major banks to retract its forecast of no rate hike next week.” · exact text match
“Based on the CPI data, the PCE Index, which is the Fed’s preferred inflation gauge (not CPI), is likely to be higher by 0.4% in August, with core up 0.3%, she added.” · exact text match
Why: Named sources, direct quotes, and concrete figures provide internal credibility; no independent external verification is visible.
Claim: The article consistently attributes substantive claims to named institutions and economists and includes a competing view.
“said the bank.” · exact text match
“said Diane Swonk, chief economist at KPMG.” · exact text match
Why: Attribution is explicit for the Goldman forecast, Thorne's critique, and Swonk's projections, and the report does not present opinions as unqualified facts.
Claim: The article uses precise quantitative distinctions and technical context.
“That would put the annualized pace of core PCE at 3.4% — far further above the Fed’s 2% target than core CPI.” · exact text match
“Super core services, she said, were up a particularly hot 0.5% and up 3% year-over-year.” · exact text match
Why: The text explains why PCE differs from CPI and cites multiple inflation measures, showing analytical depth.
The supplied text includes appended headline cards and disclosure boilerplate, so only the Fed-rate-hike item was treated as substantive article content; no external verification of the economic claims was possible.
Market/Bullish-Shock View
September 16, 2026 · 0 shares
A potential Fed rate hike is framed as a possible bullish catalyst, selecting analyst forecasts that predict a positive stock-market reaction while giving little weight to bearish scenarios.
Automated analysis; not human reviewed. Limitations: The supplied text is a partial excerpt with duplicated boilerplate, no byline or dateline, and at least one truncated quotation, so the publisher's original framing context is incomplete. · 10 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 10 scored dimensions.
Claim: The report is structured as a thesis-driven argument rather than a neutral presentation of facts.
“The case for a 'bullish shock' to stocks if the Fed hikes rates.” · exact text match
“there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The title explicitly makes a 'case,' and the content advances a contrarian interpretation using attributed analyst opinion.
Claim: The writing uses colorful and dramatic language to describe the possible market outcome.
“"Wednesday may be bullish no matter which door the FOMC walks through," Zeberg said.” · not found in supplied text
“"Falling yields and a falling dollar: the classic fuel of a bull market's final advance."” · not found in supplied text
Why: Phrases like 'bullish shock' and 'final advance' inject dramatic imagery into what is otherwise a routine market preview.
Claim: The report selects and emphasizes only bullish interpretations of a potential Fed rate hike.
“"Let's call it the bullish shock effect," he added of a potential surge in stocks on the Fed decision.” · not found in supplied text
“"Wednesday may be bullish no matter which door the FOMC walks through," Zeberg said.” · not found in supplied text
Counterevidence:
“"That's the opposite of what typically happens when the Fed hikes. Higher rates tighten financial conditions and make the macro climate less favorable to risk assets."” · not found in supplied text
Why: The lede suggests a hike 'could actually spark a renewed rally,' and every quoted forecaster predicts a positive market reaction; no bearish forecaster is included.
Claim: The forward-looking market outlook presented is uniformly positive.
“"Thus, we are expecting a positive reaction either way," Lee said.” · not found in supplied text
Why: The article's case is built around the possibility of a rally and a 'positive reaction either way,' with no pessimistic forecast featured.
Claim: The report describes possible market behavior and analyst views without telling investors what to do.
“Investors aren't clamoring for a Fed rate hike, but there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The wording is descriptive and conditional ('there's a chance,' 'if'), with no direct recommendation or imperative.
Claim: The article is a commentary-style case built on analyst opinions and forecasts.
“The case for a 'bullish shock' to stocks if the Fed hikes rates.” · exact text match
“"If the Fed hikes, this is priced in. If the Fed is on hold, it is a surprise dovish move. Thus, we are expecting a positive reaction either way," Lee said.” · not found in supplied text
Why: It argues for a specific market outlook using attributed opinions, rather than reporting a settled event.
Claim: The market reaction is reduced to a binary hike-or-hold scenario, both of which are assumed positive.
“"If the Fed hikes, this is priced in. If the Fed is on hold, it is a surprise dovish move. Thus, we are expecting a positive reaction either way," Lee said.” · not found in supplied text
Why: The quoted thesis treats only two possible Fed outcomes and ignores other variables such as forward guidance, projections, or a hawkish hold.
Claim: The report supports its thesis with named sources, direct quotes, and specific market data.
“Scott Chronert, the head of US equity strategy at Citi Research, said this week.” · exact text match
“Thomas Lee, a market permabull and the head of research at Fundstrat, said he believes markets are primed for a positive reaction no matter what the Fed does at the end of its meeting.” · exact text match
Why: Attribution is specific and quotes are direct, and the piece includes concrete probabilities and index/yield figures; credibility is limited by the one-sided selection of bullish forecasts.
Claim: The article centers on hypothetical future market reactions rather than realized outcomes.
“there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The entire piece is a pre-FOMC forecast about what could happen if the Fed hikes, holds, or signals resolve.
Claim: The article presents a structured contrarian argument with stated reasoning and supporting data.
“But there are two main reasons a hike could actually be bullish this time around, analysts say:” · exact text match
Why: It acknowledges the conventional negative view and then lays out a two-part rationale with attributed forecasts and market figures, though it does not critically test that rationale.
The supplied text is a partial excerpt with duplicated boilerplate, no byline or dateline, and at least one truncated quotation, so the publisher's original framing context is incomplete.
September 14, 2026 · 0 shares
Framing uses 'shock' and 'surprise' to turn one bank's conditional Fed-forecast into an alarming market warning.
Only the two-sentence headline/subheadline was supplied, with no body text: 'Citi says Fed rate hike could deliver stock market shock. A tougher Fed could deliver a surprise investors barely expect.'
Automated analysis; not human reviewed. Limitations: My assessment is limited to a two-sentence headline fragment; there is no article body, so scores reflect only the visible headline language, not the full reporting context. · 6 of 54 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 6 of 6 scored dimensions.
Claim: The text uses loaded, dramatic wording for a conditional market forecast.
“stock market shock” · exact text match
“surprise investors barely expect” · exact text match
Why: The words 'shock' and 'surprise' are affectively charged, elevating emotional impact over neutral reporting.
Claim: A Fed rate hike is framed as a negative shock for stocks, a bearish directional frame.
“Fed rate hike could deliver stock market shock” · exact text match
“A tougher Fed could deliver a surprise investors barely expect” · exact text match
Counterevidence:
“Citi says” · exact text match
Why: The lead attributes the shock warning to Citi, but the subheadline repeats the negative market view as the outlet's own statement, making the overall frame net bearish.
Claim: The tone is pessimistic because no positive market scenario is mentioned.
“deliver stock market shock” · exact text match
“A tougher Fed could deliver a surprise investors barely expect” · exact text match
Counterevidence:
“could” · exact text match
Why: Although 'could' introduces uncertainty, the only market outcome discussed is a negative surprise, producing a pessimistic tone.
Claim: The only scenario presented is an adverse market surprise, evoking fear of losses.
“deliver stock market shock” · exact text match
“surprise investors barely expect” · exact text match
Why: A warning phrased as a shock invites fear-oriented reading rather than a balanced assessment.
Claim: The subheadline presents a speculative market forecast as the outlet's own view.
“A tougher Fed could deliver a surprise investors barely expect” · exact text match
Why: Unlike the first sentence, the subheadline carries no attribution, so the forecast reads as the publisher's own opinion rather than reported news.
Claim: The text's core content is speculative forecasting about Fed policy and market reaction.
“Citi says Fed rate hike could deliver stock market shock” · exact text match
“A tougher Fed could deliver a surprise investors barely expect” · exact text match
Why: Both sentences describe hypothetical future events using 'could,' making speculation the central substance.
My assessment is limited to a two-sentence headline fragment; there is no article body, so scores reflect only the visible headline language, not the full reporting context.
September 17, 2026 · 0 shares
Frames the Fed's rate hike as welcomed by stocks while casting Trump's opposition as an outlier, using emotional language to create a mildly sensational, market-positive narrative.
Automated analysis; not human reviewed. Limitations: Analysis is based solely on a two-line headline; the publisher's full argument and supporting evidence were unavailable. · 3 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 3 of 3 scored dimensions.
Claim: The headline presents an interpretive, emotionally colored characterization of market and presidential reactions rather than neutral factual reporting.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: The terms 'loving' and 'hates' express subjective emotional states attributed to the stock market and Trump.
Claim: The headline uses emotional and hyperbolic language to frame the Fed rate hike and reactions.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: 'Loving' and 'hates' are emotionally charged and colloquial, turning a market reaction into a dramatic contrast.
Claim: The headline conveys a positive market outlook by describing stocks as loving the rate hike.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: Characterizing stocks as 'loving' the hike frames the market reaction favorably, giving the headline a mildly bullish tone.
Analysis is based solely on a two-line headline; the publisher's full argument and supporting evidence were unavailable.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed. Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence. · 4 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
Helium Bias
September 16, 2026 · 0 shares
A potential Fed rate hike is framed as a possible bullish catalyst, selecting analyst forecasts that predict a positive stock-market reaction while giving little weight to bearish scenarios.
Automated analysis; not human reviewed. Limitations: The supplied text is a partial excerpt with duplicated boilerplate, no byline or dateline, and at least one truncated quotation, so the publisher's original framing context is incomplete. · 10 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 10 scored dimensions.
Claim: The report is structured as a thesis-driven argument rather than a neutral presentation of facts.
“The case for a 'bullish shock' to stocks if the Fed hikes rates.” · exact text match
“there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The title explicitly makes a 'case,' and the content advances a contrarian interpretation using attributed analyst opinion.
Claim: The writing uses colorful and dramatic language to describe the possible market outcome.
“"Wednesday may be bullish no matter which door the FOMC walks through," Zeberg said.” · not found in supplied text
“"Falling yields and a falling dollar: the classic fuel of a bull market's final advance."” · not found in supplied text
Why: Phrases like 'bullish shock' and 'final advance' inject dramatic imagery into what is otherwise a routine market preview.
Claim: The report selects and emphasizes only bullish interpretations of a potential Fed rate hike.
“"Let's call it the bullish shock effect," he added of a potential surge in stocks on the Fed decision.” · not found in supplied text
“"Wednesday may be bullish no matter which door the FOMC walks through," Zeberg said.” · not found in supplied text
Counterevidence:
“"That's the opposite of what typically happens when the Fed hikes. Higher rates tighten financial conditions and make the macro climate less favorable to risk assets."” · not found in supplied text
Why: The lede suggests a hike 'could actually spark a renewed rally,' and every quoted forecaster predicts a positive market reaction; no bearish forecaster is included.
Claim: The forward-looking market outlook presented is uniformly positive.
“"Thus, we are expecting a positive reaction either way," Lee said.” · not found in supplied text
Why: The article's case is built around the possibility of a rally and a 'positive reaction either way,' with no pessimistic forecast featured.
Claim: The report describes possible market behavior and analyst views without telling investors what to do.
“Investors aren't clamoring for a Fed rate hike, but there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The wording is descriptive and conditional ('there's a chance,' 'if'), with no direct recommendation or imperative.
Claim: The article is a commentary-style case built on analyst opinions and forecasts.
“The case for a 'bullish shock' to stocks if the Fed hikes rates.” · exact text match
“"If the Fed hikes, this is priced in. If the Fed is on hold, it is a surprise dovish move. Thus, we are expecting a positive reaction either way," Lee said.” · not found in supplied text
Why: It argues for a specific market outlook using attributed opinions, rather than reporting a settled event.
Claim: The market reaction is reduced to a binary hike-or-hold scenario, both of which are assumed positive.
“"If the Fed hikes, this is priced in. If the Fed is on hold, it is a surprise dovish move. Thus, we are expecting a positive reaction either way," Lee said.” · not found in supplied text
Why: The quoted thesis treats only two possible Fed outcomes and ignores other variables such as forward guidance, projections, or a hawkish hold.
Claim: The report supports its thesis with named sources, direct quotes, and specific market data.
“Scott Chronert, the head of US equity strategy at Citi Research, said this week.” · exact text match
“Thomas Lee, a market permabull and the head of research at Fundstrat, said he believes markets are primed for a positive reaction no matter what the Fed does at the end of its meeting.” · exact text match
Why: Attribution is specific and quotes are direct, and the piece includes concrete probabilities and index/yield figures; credibility is limited by the one-sided selection of bullish forecasts.
Claim: The article centers on hypothetical future market reactions rather than realized outcomes.
“there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The entire piece is a pre-FOMC forecast about what could happen if the Fed hikes, holds, or signals resolve.
Claim: The article presents a structured contrarian argument with stated reasoning and supporting data.
“But there are two main reasons a hike could actually be bullish this time around, analysts say:” · exact text match
Why: It acknowledges the conventional negative view and then lays out a two-part rationale with attributed forecasts and market figures, though it does not critically test that rationale.
The supplied text is a partial excerpt with duplicated boilerplate, no byline or dateline, and at least one truncated quotation, so the publisher's original framing context is incomplete.
Story Blindspots
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed. Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone. · 6 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 17, 2026 · 0 shares
Frames the Fed's rate hike as welcomed by stocks while casting Trump's opposition as an outlier, using emotional language to create a mildly sensational, market-positive narrative.
Automated analysis; not human reviewed. Limitations: Analysis is based solely on a two-line headline; the publisher's full argument and supporting evidence were unavailable. · 3 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 3 of 3 scored dimensions.
Claim: The headline presents an interpretive, emotionally colored characterization of market and presidential reactions rather than neutral factual reporting.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: The terms 'loving' and 'hates' express subjective emotional states attributed to the stock market and Trump.
Claim: The headline uses emotional and hyperbolic language to frame the Fed rate hike and reactions.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: 'Loving' and 'hates' are emotionally charged and colloquial, turning a market reaction into a dramatic contrast.
Claim: The headline conveys a positive market outlook by describing stocks as loving the rate hike.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: Characterizing stocks as 'loving' the hike frames the market reaction favorably, giving the headline a mildly bullish tone.
Analysis is based solely on a two-line headline; the publisher's full argument and supporting evidence were unavailable.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed. Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence. · 4 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed. Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone. · 6 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 13, 2026 · 0 shares
Dovish framings are foregrounded, presenting the likely Fed hike as a Wall Street-driven "wall of mirrors" rather than an inflation response, while a competing forecast of further hikes is included.
Automated analysis; not human reviewed. Limitations: The supplied text includes appended headline cards and disclosure boilerplate, so only the Fed-rate-hike item was treated as substantive article content; no external verification of the economic claims was possible. · 6 of 54 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 6 of 6 scored dimensions.
Claim: The headline and lead framing assert a market-driven motive for the expected Fed hike while the article still includes attributed data.
“Fed rate hike is about Wall Street, not inflation, says economist.” · exact text match
“Fast-forward two years, and markets are assuming the Fed has no choice but to embark on a rate-hike cycle next week, even as the core CPI has fallen to a five-year low of 2.4%.” · exact text match
Why: The selection of the headline and the juxtaposition highlight an interpretive claim, but the body uses attributed quotes and includes a competing forecast.
Claim: The report relays forecasts and attributed opinions rather than issuing policy commands.
“A Federal Reserve rate hike next Wednesday — likely 25 basis points — is essentially universally expected at this point.” · exact text match
“We now expect three rate hikes by early 2027” · exact text match
Why: No publisher-authored 'should' or directive appears; evaluative lines are in quoted material.
Claim: The selected commentary stresses that rate hikes harm demand and are not an inflation cure, a dovish-leaning framing.
“No material change in inflation outlook, but a hike to calm Wall Street.” · exact text match
“They reduce demand, investment, employment, and household purchasing power.” · exact text match
Why: Thorne's critiques are given prominent placement and align with the headline; Swonk's forecast of more hikes appears later as a counterpoint.
Claim: Visible sourcing and specific statistics support the report's trustworthiness.
“Goldman Sachs late Friday became the last of the major banks to retract its forecast of no rate hike next week.” · exact text match
“Based on the CPI data, the PCE Index, which is the Fed’s preferred inflation gauge (not CPI), is likely to be higher by 0.4% in August, with core up 0.3%, she added.” · exact text match
Why: Named sources, direct quotes, and concrete figures provide internal credibility; no independent external verification is visible.
Claim: The article consistently attributes substantive claims to named institutions and economists and includes a competing view.
“said the bank.” · exact text match
“said Diane Swonk, chief economist at KPMG.” · exact text match
Why: Attribution is explicit for the Goldman forecast, Thorne's critique, and Swonk's projections, and the report does not present opinions as unqualified facts.
Claim: The article uses precise quantitative distinctions and technical context.
“That would put the annualized pace of core PCE at 3.4% — far further above the Fed’s 2% target than core CPI.” · exact text match
“Super core services, she said, were up a particularly hot 0.5% and up 3% year-over-year.” · exact text match
Why: The text explains why PCE differs from CPI and cites multiple inflation measures, showing analytical depth.
The supplied text includes appended headline cards and disclosure boilerplate, so only the Fed-rate-hike item was treated as substantive article content; no external verification of the economic claims was possible.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed. Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence. · 4 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed. Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone. · 6 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 13, 2026 · 0 shares
Dovish framings are foregrounded, presenting the likely Fed hike as a Wall Street-driven "wall of mirrors" rather than an inflation response, while a competing forecast of further hikes is included.
Automated analysis; not human reviewed. Limitations: The supplied text includes appended headline cards and disclosure boilerplate, so only the Fed-rate-hike item was treated as substantive article content; no external verification of the economic claims was possible. · 6 of 54 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 6 of 6 scored dimensions.
Claim: The headline and lead framing assert a market-driven motive for the expected Fed hike while the article still includes attributed data.
“Fed rate hike is about Wall Street, not inflation, says economist.” · exact text match
“Fast-forward two years, and markets are assuming the Fed has no choice but to embark on a rate-hike cycle next week, even as the core CPI has fallen to a five-year low of 2.4%.” · exact text match
Why: The selection of the headline and the juxtaposition highlight an interpretive claim, but the body uses attributed quotes and includes a competing forecast.
Claim: The report relays forecasts and attributed opinions rather than issuing policy commands.
“A Federal Reserve rate hike next Wednesday — likely 25 basis points — is essentially universally expected at this point.” · exact text match
“We now expect three rate hikes by early 2027” · exact text match
Why: No publisher-authored 'should' or directive appears; evaluative lines are in quoted material.
Claim: The selected commentary stresses that rate hikes harm demand and are not an inflation cure, a dovish-leaning framing.
“No material change in inflation outlook, but a hike to calm Wall Street.” · exact text match
“They reduce demand, investment, employment, and household purchasing power.” · exact text match
Why: Thorne's critiques are given prominent placement and align with the headline; Swonk's forecast of more hikes appears later as a counterpoint.
Claim: Visible sourcing and specific statistics support the report's trustworthiness.
“Goldman Sachs late Friday became the last of the major banks to retract its forecast of no rate hike next week.” · exact text match
“Based on the CPI data, the PCE Index, which is the Fed’s preferred inflation gauge (not CPI), is likely to be higher by 0.4% in August, with core up 0.3%, she added.” · exact text match
Why: Named sources, direct quotes, and concrete figures provide internal credibility; no independent external verification is visible.
Claim: The article consistently attributes substantive claims to named institutions and economists and includes a competing view.
“said the bank.” · exact text match
“said Diane Swonk, chief economist at KPMG.” · exact text match
Why: Attribution is explicit for the Goldman forecast, Thorne's critique, and Swonk's projections, and the report does not present opinions as unqualified facts.
Claim: The article uses precise quantitative distinctions and technical context.
“That would put the annualized pace of core PCE at 3.4% — far further above the Fed’s 2% target than core CPI.” · exact text match
“Super core services, she said, were up a particularly hot 0.5% and up 3% year-over-year.” · exact text match
Why: The text explains why PCE differs from CPI and cites multiple inflation measures, showing analytical depth.
The supplied text includes appended headline cards and disclosure boilerplate, so only the Fed-rate-hike item was treated as substantive article content; no external verification of the economic claims was possible.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed. Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence. · 4 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 16, 2026 · 0 shares
The coverage frames the Fed's quarter-point hike as a politically charged but market-expected move, emphasizing White House pressure and central-bank independence.
Automated analysis; not human reviewed. Limitations: The supplied text is a truncated, interleaved extraction with some incomplete paragraphs and apparent sidebar items; classification is based mainly on the clear economic and political reporting segments. · 2 of 54 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 2 scored dimensions.
Claim: The publisher asserts without hedging that the rate hike will certainly make the president angry.
“The fresh hike will be sure to anger Mr Trump” · exact text match
Why: The phrase 'will be sure to' expresses certainty about a future emotional response, which the article does not and cannot establish.
Claim: The report attributes key policy and market statements to named institutions and officials.
“according to the central bank's Summary of Economic Projections” · exact text match
“JP Morgan's global head of economic research, Bruce Kasman, said market expectations surrounding interest rates had shifted across the developed world since the beginning of the year.” · exact text match
Why: Named attribution and direct quotation provide visible sourcing for most assertions.
The supplied text is a truncated, interleaved extraction with some incomplete paragraphs and apparent sidebar items; classification is based mainly on the clear economic and political reporting segments.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed. Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone. · 6 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed. Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence. · 4 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed. Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone. · 6 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 16, 2026 · 0 shares
A potential Fed rate hike is framed as a possible bullish catalyst, selecting analyst forecasts that predict a positive stock-market reaction while giving little weight to bearish scenarios.
Automated analysis; not human reviewed.
Limitations: The supplied text is a partial excerpt with duplicated boilerplate, no byline or dateline, and at least one truncated quotation, so the publisher's original framing context is incomplete.
·
10 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 5 of 10 scored dimensions.
Claim: The report is structured as a thesis-driven argument rather than a neutral presentation of facts.
“The case for a 'bullish shock' to stocks if the Fed hikes rates.” · exact text match
“there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The title explicitly makes a 'case,' and the content advances a contrarian interpretation using attributed analyst opinion.
Claim: The writing uses colorful and dramatic language to describe the possible market outcome.
“"Wednesday may be bullish no matter which door the FOMC walks through," Zeberg said.” · not found in supplied text
“"Falling yields and a falling dollar: the classic fuel of a bull market's final advance."” · not found in supplied text
Why: Phrases like 'bullish shock' and 'final advance' inject dramatic imagery into what is otherwise a routine market preview.
Claim: The report selects and emphasizes only bullish interpretations of a potential Fed rate hike.
“"Let's call it the bullish shock effect," he added of a potential surge in stocks on the Fed decision.” · not found in supplied text
“"Wednesday may be bullish no matter which door the FOMC walks through," Zeberg said.” · not found in supplied text
Counterevidence:
“"That's the opposite of what typically happens when the Fed hikes.
Higher rates tighten financial conditions and make the macro climate less favorable to risk assets."”
· not found in supplied text
Why: The lede suggests a hike 'could actually spark a renewed rally,' and every quoted forecaster predicts a positive market reaction; no bearish forecaster is included.
Claim: The forward-looking market outlook presented is uniformly positive.
“"Thus, we are expecting a positive reaction either way," Lee said.” · not found in supplied text
Why: The article's case is built around the possibility of a rally and a 'positive reaction either way,' with no pessimistic forecast featured.
Claim: The report describes possible market behavior and analyst views without telling investors what to do.
“Investors aren't clamoring for a Fed rate hike, but there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The wording is descriptive and conditional ('there's a chance,' 'if'), with no direct recommendation or imperative.
Claim: The article is a commentary-style case built on analyst opinions and forecasts.
“The case for a 'bullish shock' to stocks if the Fed hikes rates.” · exact text match
“"If the Fed hikes, this is priced in. If the Fed is on hold, it is a surprise dovish move.
Thus, we are expecting a positive reaction either way," Lee said.”
· not found in supplied text
Why: It argues for a specific market outlook using attributed opinions, rather than reporting a settled event.
Claim: The market reaction is reduced to a binary hike-or-hold scenario, both of which are assumed positive.
“"If the Fed hikes, this is priced in. If the Fed is on hold, it is a surprise dovish move.
Thus, we are expecting a positive reaction either way," Lee said.”
· not found in supplied text
Why: The quoted thesis treats only two possible Fed outcomes and ignores other variables such as forward guidance, projections, or a hawkish hold.
Claim: The report supports its thesis with named sources, direct quotes, and specific market data.
“Scott Chronert, the head of US equity strategy at Citi Research, said this week.” · exact text match
“Thomas Lee, a market permabull and the head of research at Fundstrat, said he believes markets are primed for a positive reaction no matter what the Fed does at the end of its meeting.” · exact text match
Why: Attribution is specific and quotes are direct, and the piece includes concrete probabilities and index/yield figures; credibility is limited by the one-sided selection of bullish forecasts.
Claim: The article centers on hypothetical future market reactions rather than realized outcomes.
“there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The entire piece is a pre-FOMC forecast about what could happen if the Fed hikes, holds, or signals resolve.
Claim: The article presents a structured contrarian argument with stated reasoning and supporting data.
“But there are two main reasons a hike could actually be bullish this time around, analysts say:” · exact text match
Why: It acknowledges the conventional negative view and then lays out a two-part rationale with attributed forecasts and market figures, though it does not critically test that rationale.
The supplied text is a partial excerpt with duplicated boilerplate, no byline or dateline, and at least one truncated quotation, so the publisher's original framing context is incomplete.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed.
Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
·
4 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed.
Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
·
6 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed.
Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
·
6 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 17, 2026 · 0 shares
The framing treats the rate hike as established fact and packages the item as a promotional, expert-led video discussion of possible economic effects.
Automated analysis; not human reviewed.
Limitations: The analyzed input is only a headline and a one-sentence video description, so most bias dimensions lack evidence; the rate-hike assertion could not be independently checked from this text.
·
2 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 2 of 2 scored dimensions.
Claim: The text is packaged as promotional media content rather than independent reporting.
“Michael Spence: Fed Hikes Rates For The First Time Since 2023. (25:59)” · exact text match
Why: The headline, expert name, and runtime format serve as a teaser to attract viewers to a video conversation.
Claim: The framing emphasizes prospective, not realized, economic effects.
“how higher interest rates might impact the economy” · exact text match
Why: The phrase 'might impact' frames the topic as a forecasting discussion rather than reporting of observed economic data.
The analyzed input is only a headline and a one-sentence video description, so most bias dimensions lack evidence; the rate-hike assertion could not be independently checked from this text.
September 16, 2026 · 0 shares
The coverage frames the Fed's quarter-point hike as a politically charged but market-expected move, emphasizing White House pressure and central-bank independence.
Automated analysis; not human reviewed.
Limitations: The supplied text is a truncated, interleaved extraction with some incomplete paragraphs and apparent sidebar items; classification is based mainly on the clear economic and political reporting segments.
·
2 of 54 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 2 of 2 scored dimensions.
Claim: The publisher asserts without hedging that the rate hike will certainly make the president angry.
“The fresh hike will be sure to anger Mr Trump” · exact text match
Why: The phrase 'will be sure to' expresses certainty about a future emotional response, which the article does not and cannot establish.
Claim: The report attributes key policy and market statements to named institutions and officials.
“according to the central bank's Summary of Economic Projections” · exact text match
“JP Morgan's global head of economic research, Bruce Kasman, said market expectations surrounding interest rates had shifted across the developed world since the beginning of the year.” · exact text match
Why: Named attribution and direct quotation provide visible sourcing for most assertions.
The supplied text is a truncated, interleaved extraction with some incomplete paragraphs and apparent sidebar items; classification is based mainly on the clear economic and political reporting segments.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed.
Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
·
4 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 14, 2026 · 0 shares
Framing uses 'shock' and 'surprise' to turn one bank's conditional Fed-forecast into an alarming market warning.
Only the two-sentence headline/subheadline was supplied, with no body text: 'Citi says Fed rate hike could deliver stock market shock.
A tougher Fed could deliver a surprise investors barely expect.'
Automated analysis; not human reviewed.
Limitations: My assessment is limited to a two-sentence headline fragment; there is no article body, so scores reflect only the visible headline language, not the full reporting context.
·
6 of 54 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 6 of 6 scored dimensions.
Claim: The text uses loaded, dramatic wording for a conditional market forecast.
“stock market shock” · exact text match
“surprise investors barely expect” · exact text match
Why: The words 'shock' and 'surprise' are affectively charged, elevating emotional impact over neutral reporting.
Claim: A Fed rate hike is framed as a negative shock for stocks, a bearish directional frame.
“Fed rate hike could deliver stock market shock” · exact text match
“A tougher Fed could deliver a surprise investors barely expect” · exact text match
Counterevidence:
“Citi says” · exact text match
Why: The lead attributes the shock warning to Citi, but the subheadline repeats the negative market view as the outlet's own statement, making the overall frame net bearish.
Claim: The tone is pessimistic because no positive market scenario is mentioned.
“deliver stock market shock” · exact text match
“A tougher Fed could deliver a surprise investors barely expect” · exact text match
Counterevidence:
“could” · exact text match
Why: Although 'could' introduces uncertainty, the only market outcome discussed is a negative surprise, producing a pessimistic tone.
Claim: The only scenario presented is an adverse market surprise, evoking fear of losses.
“deliver stock market shock” · exact text match
“surprise investors barely expect” · exact text match
Why: A warning phrased as a shock invites fear-oriented reading rather than a balanced assessment.
Claim: The subheadline presents a speculative market forecast as the outlet's own view.
“A tougher Fed could deliver a surprise investors barely expect” · exact text match
Why: Unlike the first sentence, the subheadline carries no attribution, so the forecast reads as the publisher's own opinion rather than reported news.
Claim: The text's core content is speculative forecasting about Fed policy and market reaction.
“Citi says Fed rate hike could deliver stock market shock” · exact text match
“A tougher Fed could deliver a surprise investors barely expect” · exact text match
Why: Both sentences describe hypothetical future events using 'could,' making speculation the central substance.
My assessment is limited to a two-sentence headline fragment; there is no article body, so scores reflect only the visible headline language, not the full reporting context.
September 16, 2026 · 0 shares
A potential Fed rate hike is framed as a possible bullish catalyst, selecting analyst forecasts that predict a positive stock-market reaction while giving little weight to bearish scenarios.
Automated analysis; not human reviewed.
Limitations: The supplied text is a partial excerpt with duplicated boilerplate, no byline or dateline, and at least one truncated quotation, so the publisher's original framing context is incomplete.
·
10 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 5 of 10 scored dimensions.
Claim: The report is structured as a thesis-driven argument rather than a neutral presentation of facts.
“The case for a 'bullish shock' to stocks if the Fed hikes rates.” · exact text match
“there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The title explicitly makes a 'case,' and the content advances a contrarian interpretation using attributed analyst opinion.
Claim: The writing uses colorful and dramatic language to describe the possible market outcome.
“"Wednesday may be bullish no matter which door the FOMC walks through," Zeberg said.” · not found in supplied text
“"Falling yields and a falling dollar: the classic fuel of a bull market's final advance."” · not found in supplied text
Why: Phrases like 'bullish shock' and 'final advance' inject dramatic imagery into what is otherwise a routine market preview.
Claim: The report selects and emphasizes only bullish interpretations of a potential Fed rate hike.
“"Let's call it the bullish shock effect," he added of a potential surge in stocks on the Fed decision.” · not found in supplied text
“"Wednesday may be bullish no matter which door the FOMC walks through," Zeberg said.” · not found in supplied text
Counterevidence:
“"That's the opposite of what typically happens when the Fed hikes.
Higher rates tighten financial conditions and make the macro climate less favorable to risk assets."”
· not found in supplied text
Why: The lede suggests a hike 'could actually spark a renewed rally,' and every quoted forecaster predicts a positive market reaction; no bearish forecaster is included.
Claim: The forward-looking market outlook presented is uniformly positive.
“"Thus, we are expecting a positive reaction either way," Lee said.” · not found in supplied text
Why: The article's case is built around the possibility of a rally and a 'positive reaction either way,' with no pessimistic forecast featured.
Claim: The report describes possible market behavior and analyst views without telling investors what to do.
“Investors aren't clamoring for a Fed rate hike, but there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The wording is descriptive and conditional ('there's a chance,' 'if'), with no direct recommendation or imperative.
Claim: The article is a commentary-style case built on analyst opinions and forecasts.
“The case for a 'bullish shock' to stocks if the Fed hikes rates.” · exact text match
“"If the Fed hikes, this is priced in. If the Fed is on hold, it is a surprise dovish move.
Thus, we are expecting a positive reaction either way," Lee said.”
· not found in supplied text
Why: It argues for a specific market outlook using attributed opinions, rather than reporting a settled event.
Claim: The market reaction is reduced to a binary hike-or-hold scenario, both of which are assumed positive.
“"If the Fed hikes, this is priced in. If the Fed is on hold, it is a surprise dovish move.
Thus, we are expecting a positive reaction either way," Lee said.”
· not found in supplied text
Why: The quoted thesis treats only two possible Fed outcomes and ignores other variables such as forward guidance, projections, or a hawkish hold.
Claim: The report supports its thesis with named sources, direct quotes, and specific market data.
“Scott Chronert, the head of US equity strategy at Citi Research, said this week.” · exact text match
“Thomas Lee, a market permabull and the head of research at Fundstrat, said he believes markets are primed for a positive reaction no matter what the Fed does at the end of its meeting.” · exact text match
Why: Attribution is specific and quotes are direct, and the piece includes concrete probabilities and index/yield figures; credibility is limited by the one-sided selection of bullish forecasts.
Claim: The article centers on hypothetical future market reactions rather than realized outcomes.
“there's a chance an increase in interest rates could actually spark a renewed rally in stocks, according to some forecasters.” · exact text match
Why: The entire piece is a pre-FOMC forecast about what could happen if the Fed hikes, holds, or signals resolve.
Claim: The article presents a structured contrarian argument with stated reasoning and supporting data.
“But there are two main reasons a hike could actually be bullish this time around, analysts say:” · exact text match
Why: It acknowledges the conventional negative view and then lays out a two-part rationale with attributed forecasts and market figures, though it does not critically test that rationale.
The supplied text is a partial excerpt with duplicated boilerplate, no byline or dateline, and at least one truncated quotation, so the publisher's original framing context is incomplete.
September 17, 2026 · 0 shares
Frames the Fed's rate hike as welcomed by stocks while casting Trump's opposition as an outlier, using emotional language to create a mildly sensational, market-positive narrative.
Automated analysis; not human reviewed.
Limitations: Analysis is based solely on a two-line headline; the publisher's full argument and supporting evidence were unavailable.
·
3 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 3 of 3 scored dimensions.
Claim: The headline presents an interpretive, emotionally colored characterization of market and presidential reactions rather than neutral factual reporting.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: The terms 'loving' and 'hates' express subjective emotional states attributed to the stock market and Trump.
Claim: The headline uses emotional and hyperbolic language to frame the Fed rate hike and reactions.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: 'Loving' and 'hates' are emotionally charged and colloquial, turning a market reaction into a dramatic contrast.
Claim: The headline conveys a positive market outlook by describing stocks as loving the rate hike.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: Characterizing stocks as 'loving' the hike frames the market reaction favorably, giving the headline a mildly bullish tone.
Analysis is based solely on a two-line headline; the publisher's full argument and supporting evidence were unavailable.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed.
Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
·
4 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 13, 2026 · 0 shares
Dovish framings are foregrounded, presenting the likely Fed hike as a Wall Street-driven "wall of mirrors" rather than an inflation response, while a competing forecast of further hikes is included.
Automated analysis; not human reviewed.
Limitations: The supplied text includes appended headline cards and disclosure boilerplate, so only the Fed-rate-hike item was treated as substantive article content; no external verification of the economic claims was possible.
·
6 of 54 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 6 of 6 scored dimensions.
Claim: The headline and lead framing assert a market-driven motive for the expected Fed hike while the article still includes attributed data.
“Fed rate hike is about Wall Street, not inflation, says economist.” · exact text match
“Fast-forward two years, and markets are assuming the Fed has no choice but to embark on a rate-hike cycle next week, even as the core CPI has fallen to a five-year low of 2.4%.” · exact text match
Why: The selection of the headline and the juxtaposition highlight an interpretive claim, but the body uses attributed quotes and includes a competing forecast.
Claim: The report relays forecasts and attributed opinions rather than issuing policy commands.
“A Federal Reserve rate hike next Wednesday — likely 25 basis points — is essentially universally expected at this point.” · exact text match
“We now expect three rate hikes by early 2027” · exact text match
Why: No publisher-authored 'should' or directive appears; evaluative lines are in quoted material.
Claim: The selected commentary stresses that rate hikes harm demand and are not an inflation cure, a dovish-leaning framing.
“No material change in inflation outlook, but a hike to calm Wall Street.” · exact text match
“They reduce demand, investment, employment, and household purchasing power.” · exact text match
Why: Thorne's critiques are given prominent placement and align with the headline; Swonk's forecast of more hikes appears later as a counterpoint.
Claim: Visible sourcing and specific statistics support the report's trustworthiness.
“Goldman Sachs late Friday became the last of the major banks to retract its forecast of no rate hike next week.” · exact text match
“Based on the CPI data, the PCE Index, which is the Fed’s preferred inflation gauge (not CPI), is likely to be higher by 0.4% in August, with core up 0.3%, she added.” · exact text match
Why: Named sources, direct quotes, and concrete figures provide internal credibility; no independent external verification is visible.
Claim: The article consistently attributes substantive claims to named institutions and economists and includes a competing view.
“said the bank.” · exact text match
“said Diane Swonk, chief economist at KPMG.” · exact text match
Why: Attribution is explicit for the Goldman forecast, Thorne's critique, and Swonk's projections, and the report does not present opinions as unqualified facts.
Claim: The article uses precise quantitative distinctions and technical context.
“That would put the annualized pace of core PCE at 3.4% — far further above the Fed’s 2% target than core CPI.” · exact text match
“Super core services, she said, were up a particularly hot 0.5% and up 3% year-over-year.” · exact text match
Why: The text explains why PCE differs from CPI and cites multiple inflation measures, showing analytical depth.
The supplied text includes appended headline cards and disclosure boilerplate, so only the Fed-rate-hike item was treated as substantive article content; no external verification of the economic claims was possible.
September 16, 2026 · 0 shares
The coverage frames the Fed's quarter-point hike as a politically charged but market-expected move, emphasizing White House pressure and central-bank independence.
Automated analysis; not human reviewed.
Limitations: The supplied text is a truncated, interleaved extraction with some incomplete paragraphs and apparent sidebar items; classification is based mainly on the clear economic and political reporting segments.
·
2 of 54 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 2 of 2 scored dimensions.
Claim: The publisher asserts without hedging that the rate hike will certainly make the president angry.
“The fresh hike will be sure to anger Mr Trump” · exact text match
Why: The phrase 'will be sure to' expresses certainty about a future emotional response, which the article does not and cannot establish.
Claim: The report attributes key policy and market statements to named institutions and officials.
“according to the central bank's Summary of Economic Projections” · exact text match
“JP Morgan's global head of economic research, Bruce Kasman, said market expectations surrounding interest rates had shifted across the developed world since the beginning of the year.” · exact text match
Why: Named attribution and direct quotation provide visible sourcing for most assertions.
The supplied text is a truncated, interleaved extraction with some incomplete paragraphs and apparent sidebar items; classification is based mainly on the clear economic and political reporting segments.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed.
Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
·
6 of 55 available dimensions scored; omitted dimensions are not treated as neutral.
·
Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed. Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone. · 6 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 16, 2026 · 0 shares
Reporting emphasizes the Fed's unanimous, hawkish resolve and credibility while noting economists' doubts about the hike's necessity.
Automated analysis; not human reviewed. Limitations: The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone. · 6 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 5 of 6 scored dimensions.
Claim: The report is predominantly factual but contains a mild editorial characterization.
“The US Federal Reserve on Wednesday raised its interest rate by 25 basis points to 3.75-4%, its first hike since July 2023, to combat persistent inflation.” · exact text match
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: Most statements are attributed or quantitative, but 'positive spin' is a subjective characterization of Warsh's remarks.
Claim: The article uses sober, data-heavy language rather than sensational phrasing.
“The FOMC's updated projections showed most officials expected the policy rate to reach 4-4.25% by the end of 2026, as supply shocks and geopolitical pressures drive inflation.” · exact text match
Why: No dramatic or emotive language; content centers on rates, projections, and market figures.
Claim: The report mostly relays facts and attributed views, with one editorial characterization.
“Warsh put a positive spin, saying a robust and resilient economy can handle a quarter-point hike.” · exact text match
Why: The phrase 'positive spin' is an evaluative characterization rather than a neutral description, but it is isolated.
Claim: The report attributes key assertions, includes projections, and gives room to dissenting economists.
“The FOMC voted unanimously, 12-0, at a meeting held on September 15-16.” · not found in supplied text
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: Specific numbers, named institutions, and direct quotes support verifiability, while inclusion of skeptics improves balance.
Claim: The article relays analyst forecasts about future rate moves.
“Analysts read the unanimous 12-0 vote as hawkish, suggesting at least one more rate hike before year end.” · exact text match
“Goldman Sachs, JPMorgan Chase and Morgan Stanley also turned more hawkish, anticipating further monetary tightening.” · exact text match
Why: These statements are forecasts attributed to analysts rather than established facts.
Claim: The piece integrates projections, market data, and contrasting expert views.
“Inflation, as measured by the personal consumption expenditures price index, was projected to reach 3.7% in 2026, up from the June forecast of 3.6%, and remained unchanged at 2.3% for 2027.” · exact text match
“Some economists, though, have questioned whether the hike was necessary, arguing that recent core price rises stem largely from temporary or supply-side shocks rather than an overheated, demand-driven domestic economy.” · exact text match
Why: The report combines quantitative forecasts, market moves, and opposing interpretations in a compact narrative.
The supplied text is a future-dated (September 2026) report whose claims, quotes, and market figures cannot be independently checked from the text alone.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed. Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence. · 4 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 16, 2026 · 0 shares
The coverage frames the Fed's quarter-point hike as a politically charged but market-expected move, emphasizing White House pressure and central-bank independence.
Automated analysis; not human reviewed. Limitations: The supplied text is a truncated, interleaved extraction with some incomplete paragraphs and apparent sidebar items; classification is based mainly on the clear economic and political reporting segments. · 2 of 54 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 2 scored dimensions.
Claim: The publisher asserts without hedging that the rate hike will certainly make the president angry.
“The fresh hike will be sure to anger Mr Trump” · exact text match
Why: The phrase 'will be sure to' expresses certainty about a future emotional response, which the article does not and cannot establish.
Claim: The report attributes key policy and market statements to named institutions and officials.
“according to the central bank's Summary of Economic Projections” · exact text match
“JP Morgan's global head of economic research, Bruce Kasman, said market expectations surrounding interest rates had shifted across the developed world since the beginning of the year.” · exact text match
Why: Named attribution and direct quotation provide visible sourcing for most assertions.
The supplied text is a truncated, interleaved extraction with some incomplete paragraphs and apparent sidebar items; classification is based mainly on the clear economic and political reporting segments.
September 17, 2026 · 0 shares
Framing treats the Fed's hawkish rate rise as a credibility-restoring act of independence from White House pressure, while relying on expert commentary and inflation data as the interpretive lens.
Automated analysis; not human reviewed. Limitations: The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence. · 4 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 2 of 4 scored dimensions.
Claim: The framing is mildly hawkish, presenting Warsh's commitment to inflation-fighting as credibility-enhancing.
“Warsh's commitment to subduing inflation is upping his credibility among investors — a vital reputational resource in how Fed officials manage expectations about the economy.” · exact text match
Why: The publisher's own voice evaluates the hawkish posture positively rather than neutrally.
Claim: The report is heavily political, centering on conflict between President Trump and the Federal Reserve over interest-rate policy.
“Mr. Trump on Wednesday afternoon posted on social media that he believes interest rates should "1% or less, because we are the Best Credit in the World — BY FAR."” · not found in supplied text
“Economists interpreted Warsh's comments about inflation as signaling the Fed is willing to do whatever it takes to reduce inflation, even if that means going against the White House.” · exact text match
Why: The article frames a monetary-policy decision as a dispute with the White House, quoting Trump's demand for far lower rates and analysts' praise for defying him.
Claim: The report exhibits high evidentiary credibility through named experts, attributed analysis, and attributed data.
“Gasoline reached $4.44 a gallon, 38% higher than a year earlier, according to AAA data.” · exact text match
“Tim Duy, chief U.S. economist at SGH Macro Advisors, told clients in a research note.” · exact text match
Why: Specific figures are attributed to a named data source and interpretive claims are attributed to named economists, supporting visible reliability.
Claim: The report shows fair, non-deceptive handling of quoted opinions and data attribution.
“"Hiking was the right move, and it restores Fed credibility that the central bank will curb inflation no matter what the White House or anyone else says," Heather Long, chief economist at the Navy Federal Credit Union, said in an email.” · not found in supplied text
Why: A normative endorsement is clearly attributed to a named source rather than presented as the publisher's own assertion.
The future-dated nature of the report (September 2026) prevents external verification, so judgments rest solely on the supplied text's internal evidence.
September 17, 2026 · 0 shares
Frames the Fed's rate hike as welcomed by stocks while casting Trump's opposition as an outlier, using emotional language to create a mildly sensational, market-positive narrative.
Automated analysis; not human reviewed. Limitations: Analysis is based solely on a two-line headline; the publisher's full argument and supporting evidence were unavailable. · 3 of 55 available dimensions scored; omitted dimensions are not treated as neutral. · Verified supporting quotes for 3 of 3 scored dimensions.
Claim: The headline presents an interpretive, emotionally colored characterization of market and presidential reactions rather than neutral factual reporting.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: The terms 'loving' and 'hates' express subjective emotional states attributed to the stock market and Trump.
Claim: The headline uses emotional and hyperbolic language to frame the Fed rate hike and reactions.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: 'Loving' and 'hates' are emotionally charged and colloquial, turning a market reaction into a dramatic contrast.
Claim: The headline conveys a positive market outlook by describing stocks as loving the rate hike.
“Why Stocks Are Loving the Fed's Rate Hike Even If Trump Hates It” · exact text match
Why: Characterizing stocks as 'loving' the hike frames the market reaction favorably, giving the headline a mildly bullish tone.
Analysis is based solely on a two-line headline; the publisher's full argument and supporting evidence were unavailable.
2026 © Helium Trades
Privacy Policy & Disclosure
* Disclaimer: Nothing on this website constitutes investment advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. Helium Trades is not responsible in any way for the accuracy
of any model predictions or price data. Any mention of a particular security and related prediction data is not a recommendation to buy or sell that security. Investments in securities involve the risk of loss. Past performance is no guarantee of future results. Helium Trades is not responsible for any of your investment decisions,
you should consult a financial expert before engaging in any transaction.
Helium Research Assistant
How can I help you today?
Ask any question about this page.